

UKG Wallet
4.5

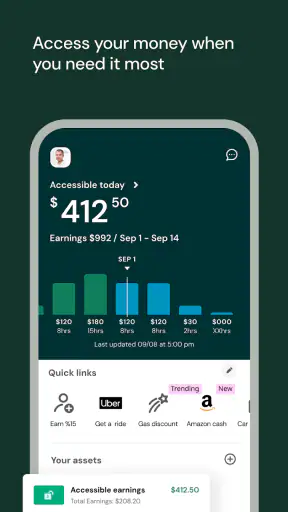
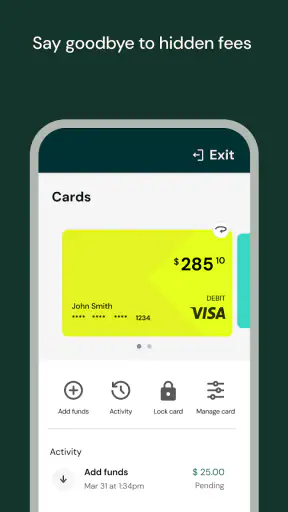
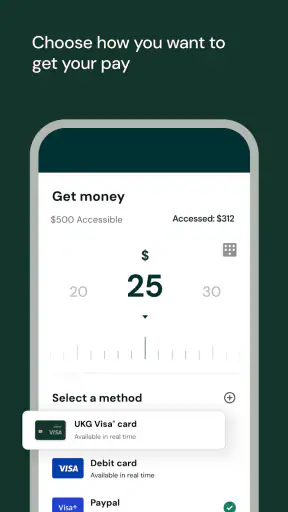
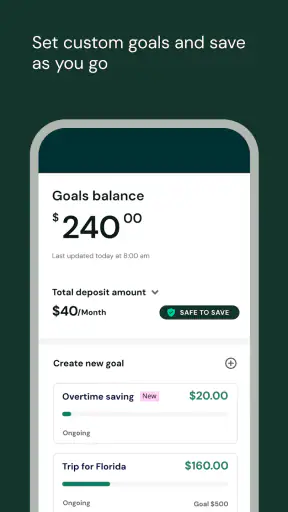
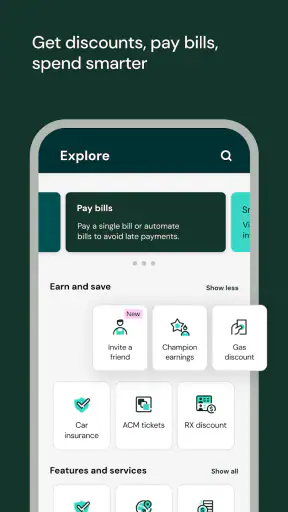
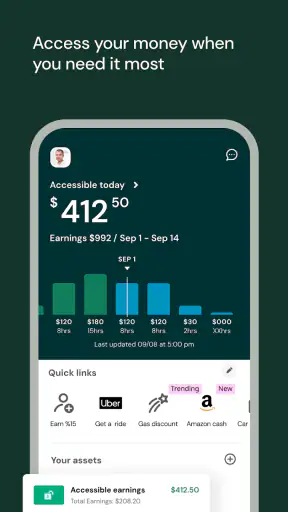
Getting paid for work and actually having access to that money are not always the same thing. UKG Wallet is a business app built around that gap: it gives eligible employees access to wages they have already earned, rather than making them wait for the normal payday. I found its main idea easy to understand, but its usefulness depends heavily on how an employer has configured the service and whether the user’s workplace supports it.
That distinction matters. This is not a general banking app, a budgeting suite, or a replacement for a payroll department. It is a focused tool for handling earned wages through an employer-connected system. UKG, Inc. develops it, and the app sits in the Business category. It is free to install, rated for Everyone, and its store presence includes over one hundred thousand installs, a four-and-a-half average from around twelve thousand ratings, and roughly two thousand written reviews.
In my experience, the strongest reason to consider it is simple: when an unexpected expense arrives before payday, access to money already earned can be more useful than advice about saving money later. That does not make every withdrawal a good idea, and it does not remove the need to manage regular income carefully. It does, however, create a practical option for people whose pay schedule does not line up with their bills.
Earned wages are the whole point
The central capability is early access to earned wages. Instead of treating the upcoming paycheck as one distant amount, the app is designed to let a worker use money associated with completed work before the regular pay date arrives. That is a much narrower purpose than the broad “money management” label used by many financial apps, and I think that narrow focus is both its biggest strength and its clearest limitation.
The benefit is easiest to see in a realistic everyday situation. Imagine that I have worked several shifts, but my phone bill or a necessary grocery trip comes due before payday. A conventional banking app can show me my current balance, while a budgeting app can warn me about the shortfall. Neither one changes when my wages arrive. UKG Wallet addresses that timing problem by putting the earned-wage option in the same place where I can review the available amount and decide whether using part of it makes sense.
That does not mean the app creates extra income. It changes access to money connected to work I have already completed. I would treat it as a timing tool, not a raise and not a substitute for an emergency fund. The distinction is important because frequent early access can make the next scheduled paycheck feel smaller, even when total earnings have not changed.
The app is most compelling for workers who experience a recurring mismatch between income dates and essential expenses. Hourly employees, people with variable schedules, and anyone handling occasional short-term gaps may find the feature more meaningful than someone with ample savings and a predictable cash flow. For the latter group, a normal bank account and automatic savings plan may be simpler.
What the focused design gets right
Because the app concentrates on earned wages, I do not expect it to compete with a full bank account. That is actually helpful when the immediate question is, “Can I access part of what I have already earned?” A focused screen can reduce the distraction found in financial apps packed with cards, investments, spending categories, and promotional offers.
There is also a useful psychological advantage to separating earned money from projected income. When I think about an entire upcoming paycheck, it is easy to mentally spend the same dollars twice. Looking at wages connected to work already completed encourages a more grounded decision. I can ask whether the current need is important enough to reduce what will remain for the regular pay cycle.
My practical tip is to use the app as a checkpoint rather than an automatic solution. Before requesting access, I would first identify the exact expense, check what must remain for rent or other fixed commitments, and decide whether the problem is a one-off timing issue or part of a larger monthly shortfall. The app can help with the first problem; it cannot solve the second.
How the experience fits into a work routine
UKG Wallet is not useful in isolation. Its value comes from the connection between the app and the employer’s payroll setup. That means the first question for a potential user is not simply whether the app can be downloaded. It is whether the person’s workplace participates and whether the worker is eligible under that arrangement.
Once that connection is in place, the sensible workflow is to open the app when a cash-flow issue appears, review the amount associated with earned wages, and consider the effect on the next regular payment. I would avoid treating the displayed amount as spending money without checking the surrounding context. A figure that looks available may still need to be weighed against upcoming obligations and personal limits.
This employer connection is also why two people can have very different experiences with the same app. One employee may find the wallet immediately relevant, while another may install it and discover that it does not fit their workplace situation. That is not a flaw in the core concept, but it does make the app less universally useful than a standard banking application.
Another practical point is timing. Earned-wage access is most valuable when I use it before a payment becomes urgent, not after a missed bill has already created a bigger problem. I would check the app early in the day, review the amount carefully, and leave enough room for the next pay cycle. That small habit turns the app from a panic button into a controlled cash-flow decision.
Questions I would answer before relying on it
A common concern is whether using the app changes total pay. The sensible way to view it is as earlier access to wages already earned, not additional earnings. If I use part of that money early, I should expect the later regular payment to reflect that earlier access. Anyone who needs a larger paycheck every pay period, rather than earlier access to the same income, should not mistake this app for a permanent income solution.
Another question is whether it replaces a bank account. In my view, it does not. A bank account remains the better place for broader money management, recurring payments, savings, and a complete record of personal finances. UKG Wallet has a more specific role: helping an eligible worker reach earned wages through an employer-linked experience.
People also reasonably wonder whether it is suitable for emergencies. It can be useful for a short gap involving a necessary expense, but I would be cautious about using it repeatedly for discretionary purchases. The convenience can hide the fact that the next pay period has less flexibility. If the same emergency appears every month, a spending review or conversation with a financial adviser would be more appropriate than repeatedly drawing wages forward.
Finally, I would not assume that installing the app guarantees immediate access. The workplace relationship matters, and the experience can depend on the employer’s arrangement and the worker’s eligibility. That is the key practical check to make before building a financial routine around it.
The best scenario is a short, specific gap
The strongest use case is a worker who has already completed enough work to earn wages but faces a necessary expense before the scheduled payday. Consider a retail employee whose weekly hours have been completed, yet a transport cost appears before the normal payroll date. Accessing part of the earned amount may prevent a missed shift or an avoidable late payment.
In that situation, I would use the app with a three-step habit. First, I would name the expense and confirm that it is essential. Second, I would take only what is needed rather than treating the full available amount as an invitation. Third, I would record the decision somewhere outside the app so I remember that the next regular pay may be lower.
That last step is easy to overlook. A wallet can make a financial action feel complete as soon as the money is accessible, but the consequences continue into the next pay cycle. Writing down the amount and the reason for using it gives the feature a little friction, and in this case friction is useful. It turns an impulsive tap into a deliberate choice.
The app could also help someone whose work hours vary from week to week and who wants to understand the relationship between completed shifts and available wages. I would still avoid using the displayed amount as a forecast of future income. Variable schedules can change, and money earned so far is not the same as money expected later.
The trade-off is convenience versus future flexibility
The main limitation is not that the feature is difficult to understand. It is that easier access can encourage earlier spending. If I use earned wages several times during a pay period, the regular payday may arrive with less money available for larger commitments. That can create a cycle in which the app solves today’s shortage while making the next shortage more likely.
This is where UKG Wallet differs from a traditional savings buffer. Savings absorb an expense without reducing the next paycheck. Earned-wage access brings forward money that would otherwise arrive later. Neither approach is automatically right or wrong, but they serve different financial situations. I would prefer savings for planned costs and reserve the app for timing problems that are genuinely short-term.
It also differs from a credit card or overdraft. Those alternatives may cover a gap but can introduce borrowing obligations and other costs. UKG Wallet’s appeal is that it is tied to wages already earned rather than a conventional credit limit. Still, “not borrowing in the usual sense” should not be confused with “free money.” The personal trade-off remains the same: less cash is left for the later pay date.
Compared with a budgeting app, UKG Wallet is more direct but much less comprehensive. A budgeting tool can help identify patterns, plan categories, and prepare for recurring bills. This app is better when the immediate issue is access to earned pay. If I need to understand why I am short every month, I would choose a budgeting system alongside it, not rely on the wallet alone.
Compared with a standard payroll portal, the wallet concept is more action-oriented. A payroll portal is usually where I look for pay information and employment records; this app is centered on what I can do with wages earned so far. That focus is convenient, but it also means I should not expect it to replace every payroll or banking task.
Small habits make the feature safer to use
My first recommendation is to set a personal limit before opening the app during a stressful moment. The available amount can answer what is possible, but it should not decide what is sensible. A fixed rule, such as using the feature only for essential expenses, gives the convenience a boundary.
My second recommendation is to check the next pay cycle immediately after making a decision. I would write down the amount, the expense, and the date of the ordinary payday. This is especially important for workers with changing hours, because the next payment may already be less predictable than usual.
My third recommendation is to compare repeated use with the cost of fixing the underlying issue. If I keep accessing wages for groceries, transport, or utilities, the pattern may point to an income or budgeting problem that the app cannot address. In that case, a conversation with an employer about pay timing, a more detailed budget, or a separate emergency fund may be a better long-term move.
I would also keep the app’s role narrow. It is tempting to check it whenever money feels tight, but frequent checking can turn a helpful option into a default spending source. I prefer to open it only when I have a defined need and a clear repayment-in-time plan, meaning I understand how the next payday will be affected.
Who will benefit most from UKG Wallet?
The best fit is an eligible employee who has a reliable connection to payroll but occasionally needs access before the normal pay date. That person is likely to appreciate a focused business app more than a broad financial platform, especially when the problem is timing rather than a lack of awareness about spending.
It may also suit someone who wants a practical alternative to using credit for a small, necessary expense. The important condition is discipline: the user must be comfortable treating early access as a shift in timing, not as extra income. A worker who can make that distinction may find the app genuinely useful during short gaps.
I would be more hesitant to recommend it to someone already relying on early access for routine bills. In that situation, the app could make the underlying imbalance less visible. I would also point people with complex financial needs toward a full banking and budgeting setup, because UKG Wallet is not designed to be their entire financial system.
The app is free to install, runs on devices using Android ten or later, and its current version is 1.0.25. Those details make it reasonably approachable for compatible users, while the Everyone content rating keeps it open to a broad audience. The more important qualification, however, is still workplace eligibility rather than the download itself.
My final view after focusing on its real purpose
UKG Wallet succeeds when I judge it by its actual job: helping an eligible worker access earned wages before the ordinary payday. It is not trying to be a complete bank, a detailed budget planner, or a financial education platform. That narrow purpose gives it a clear advantage in a specific moment, especially when a necessary expense arrives after work has been completed but before payroll is scheduled.
I would recommend it to a friend who has occasional cash-flow gaps and can use the feature with a written limit and a plan for the next pay cycle. I would not recommend treating it as a routine extension of every paycheck. The convenience is real, but so is the trade-off, and the app works best when the user remembers both sides.
For the right employee, this is a practical Business app from UKG, Inc. with a focused answer to a common problem. For someone seeking broad financial control, a normal bank account paired with budgeting tools will be the better choice. Its real value is not making money appear; it is giving earned money a more flexible timetable.
4.5
1.86K Reviews
Pros
- Supports convenient digital access to workplace pay and HR information.
- Can reduce the need for paper documents and manual administrative requests.
- Useful for employees who manage work-related details while away from a computer.
- Provides a centralized mobile experience for supported UKG services.
- May offer timely alerts and updates
- depending on employer configuration.
Cons
- Features vary significantly depending on the employer’s UKG setup.
- Requires employer credentials and may be unusable without organizational access.
- Some functions may redirect to web pages rather than feel fully native.
- Login or verification issues can prevent access when workplace systems are unavailable.
- Background notifications and account access may require additional device permissions.


